How tax can shape your investment returns over time
Tax can have a significant impact on how investments grow over time. Understanding how different investment structures are taxed can help explain how much of an investment’s earnings you get to keep.
Broadly speaking, there is no end to the different investments you can hold, from cash and term deposits, through to property, shares, commodities, infrastructure and many more.
One of the main objectives for investing money is to make money, so the impact of how your money is taxed can make a significant difference to what you actually end up with. The tax you pay can also vary depending on how you hold your investments, whether in your own name, through super, a trust or a company.
How your investments can grow
Investment returns generally come from two sources:
- Income – this could be interest, rent, or dividends from shares
- Growth – this is the increase in value of your investment, also known as a 'capital gain'
These two sources of investment returns both potentially attract tax, and how much tax you pay depends on how you ‘hold’ these investments.
Where you ‘hold’ your investment matters
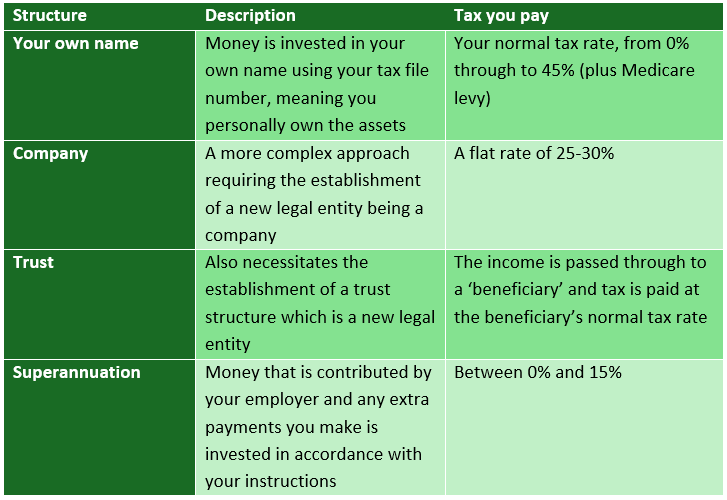
There are four common ways to hold investments in Australia, all under a different tax ‘structure’. These are: in your personal name, through a company, through a trust, or in a superannuation fund.
Each of these structures attracts a different tax treatment.
How investments are taxed
The two different ways you earn money through your investments attract a different type of tax:
- Tax on income – interest, rent or dividends are taxed in the year the income is received, at the rate of the structure in which it is held. In your own name it could be as high as 45%, in super it could be as low as 0%. By paying less tax on the same income, you get to keep more of it.
- Capital Growth – when an asset you hold increases in value and you sell it, you pay tax on that gain, again at the rate for your structure. The rules are changing from 1 July 2027, where your Capital Gains Tax liability is likely to be higher than it is today, so it's worth understanding what this means for you.
The impact of tax over time on your investments
Let’s compare two options: say you invest $10,000 and it grows at 7% a year, with tax paid annually: 37% if held in your own name, 15% if held in super. The table below shows the impact tax can have on your investment returns over time.
This example is for illustrative purposes only and assumes a constant annual return of 7% and tax paid on investment earnings each year. Actual investment returns and tax outcomes will vary.
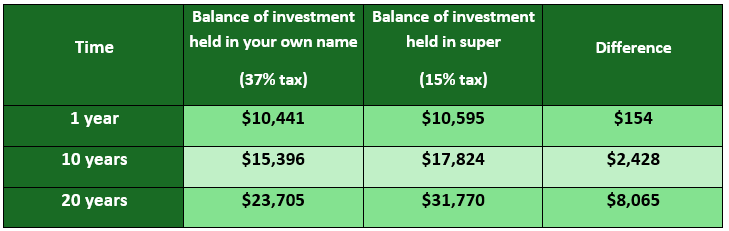
This is why it matters how much tax you pay. By investing the same amount, in the same investments, for the same period of time – just one in super and one in your own name, over 20 years that is an extra $8,065 in your pocket rather than handing it over to the tax man.
Read more about why your investment option matters.
The tax advantages of super
The changes to capital gains tax announced in the May 2026 Budget, effective from 1 July 2027, have cemented super as one of the most tax-effective places to invest. Paying less tax on your investments means more of your hard-earned money stays in your pocket, helping to maximise your investment returns over the long term. The amount of tax you pay within super will depend on a range of factors, including whether you're saving for retirement or drawing an income stream. Learn more about how super is taxed.
How NGS Advice can help you understand tax and super
Whether you’re thinking about how you invest, reviewing your investment options or wanting to better understand how tax may impact your choices, we’re here to help.
Our enhanced advice offering makes it easier to access clear, practical support and advice digitally, over the phone or face-to-face.
NGS Financial Advice can support members with:
- investment choices
- growing super balance with extra contributions
- retirement planning
- maximising retirement income
- broader superannuation and financial decisions
We believe quality financial advice should be accessible to all, so many of our advice services are complimentary, at no extra cost. So why not take the next step and see how NGS can help you make the most of your super?
This is general information only and does not take into account your objectives, financial situation or needs. Before acting on this information, or making an investment decision, consider whether it is appropriate to you and read our Product Disclosure Statements and Target Market Determinations. You should also consider obtaining financial, taxation and/or legal advice tailored to your personal circumstances before making a decision. This information has been issued by NGS Super Pty Ltd ABN 46 003 491 487 and AFSL 233 154.
Call us on 1300 133 177 if you would like to speak with us further, or you can discuss matters with one of our NGS Super Specialists or an NGS Financial Planner
Do you have an idea for a story?Email rcox@intermedia.com.au